
Categories
Real Estate Teams and Agents, San Antonio Real EstatePublished November 6, 2026
What Should Military Families Know About Buying a Home Near San Antonio?
Rise Property Group · Boerne, Texas
What Should Military Families Know About Buying a Home Near San Antonio?
Most service members and veterans can buy a home around San Antonio with no down payment and no monthly mortgage insurance using a VA loan. The benefit can be reused more than once, and in many cases a buyer can take over a seller's existing VA loan at the rate it was written at. What costs families money is not the loan itself. It is starting too late and not knowing which rules actually apply to them.

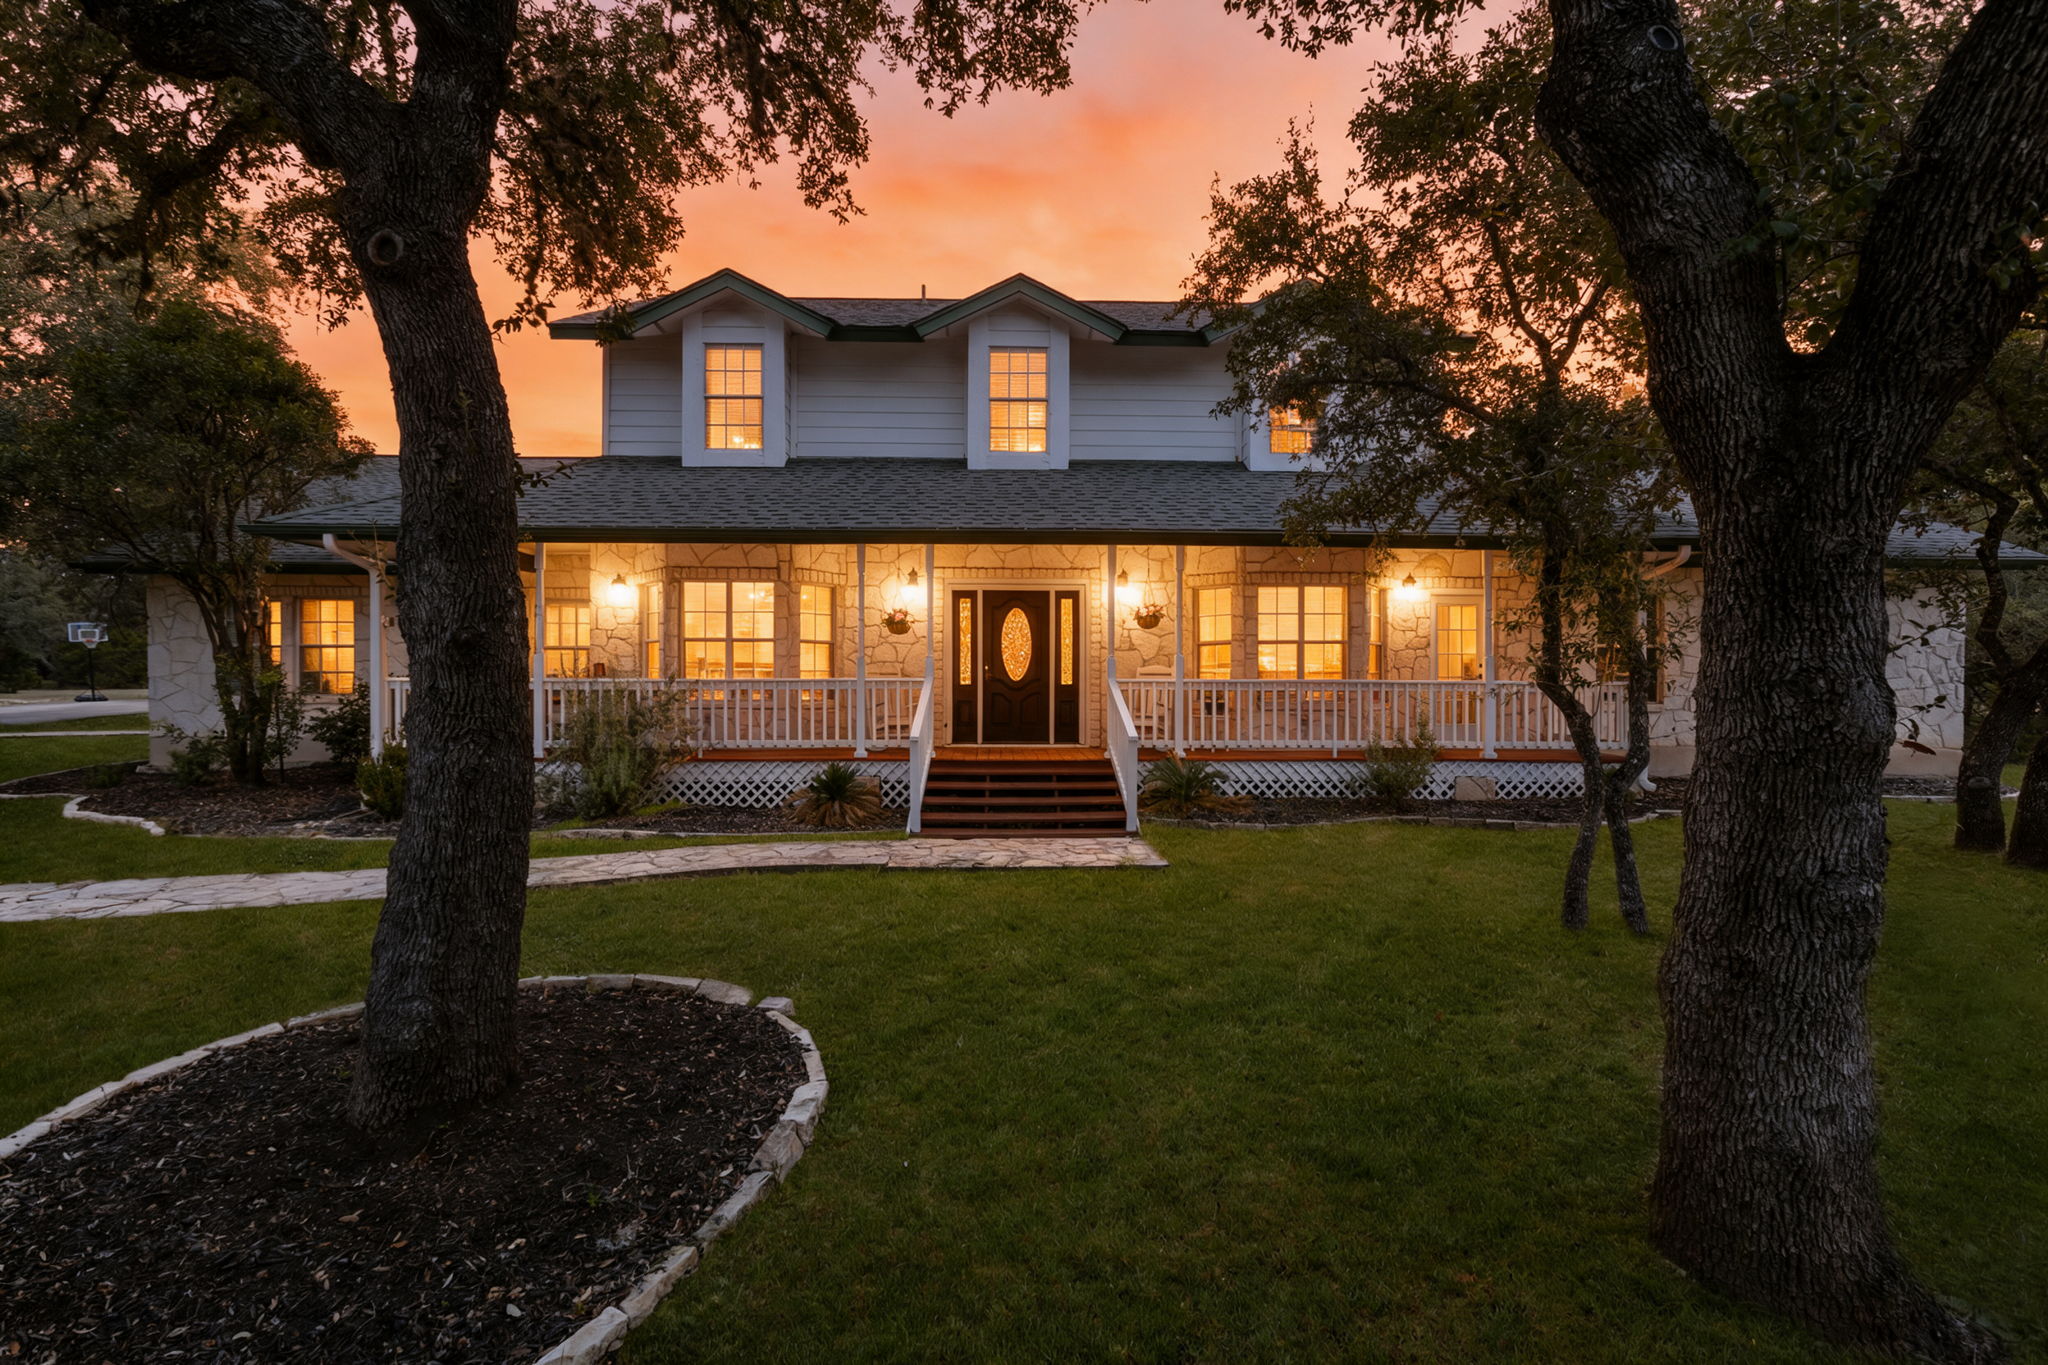
A Boerne listing represented by Rise Property Group.
This part of Texas is a military town whether or not it thinks of itself that way. Between Fort Sam Houston, Randolph, and Lackland, a steady share of the families moving through Boerne, Fair Oaks Ranch, and the north side of San Antonio are moving on orders rather than by choice of timing.
We work with those families often enough at Rise Property Group to see the same four things catch people off guard. None of them are secrets. They are published VA rules. They just tend to get explained badly, or late, or by someone who has never had to live a permanent change of station timeline.
The Short Version
- A VA purchase loan requires no down payment and carries no monthly mortgage insurance.
- There is a one-time funding fee, currently 2.15 percent of the loan on a first use with nothing down. Many disabled veterans are exempt entirely.
- The benefit is not one and done. Entitlement is usually restored once a prior VA loan is paid off.
- VA loans are assumable, which can transfer a below-market rate. The catch is that the buyer owes the seller's equity in cash at closing.
- Get pre-approved before orders are final. The VA appraisal runs on its own schedule regardless of your report date.
What is a VA loan, and who qualifies for one?
A VA loan is a mortgage issued by a private lender and guaranteed in part by the U.S. Department of Veterans Affairs. That guarantee is what lets lenders offer terms no conventional loan matches: no down payment, no private mortgage insurance, and generally competitive rates.
Eligibility runs through service history. Active-duty service members, veterans, National Guard and Reserve members with qualifying service, and many surviving spouses can qualify. The document that proves it is a Certificate of Eligibility, and a VA-approved lender can usually pull one in minutes.
One point worth stating plainly: the absence of a down payment does not mean the absence of closing costs. You will still have an appraisal, title work, prepaid taxes and insurance, and the funding fee covered below.
How much is the VA funding fee?
The funding fee is a one-time charge that goes to the VA to keep the program running without taxpayer subsidy. For a purchase loan it currently works out like this:
| Down payment | First use | Subsequent use |
|---|---|---|
| None | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
On a $450,000 purchase with nothing down, a first-use fee of 2.15 percent is roughly $9,675. It can be rolled into the loan rather than paid at the table.
The part that surprises people most often is the exemption. Veterans receiving compensation for a service-connected disability are generally exempt from the funding fee entirely, as are Purple Heart recipients and many eligible surviving spouses. So are veterans who would be receiving disability compensation except that they are drawing retirement pay instead. Only the VA makes that determination, and your lender confirms it through your Certificate of Eligibility. If a disability claim is still pending when you close, the fee is usually collected and may be refunded later if the claim is granted.
If nobody has asked you whether you are exempt, ask them.
Can you use a VA loan more than once?
Yes, and this is the single most common piece of bad information we hear. Plenty of families believe they spent their benefit on a house at a previous duty station and that was the end of it.
Entitlement is typically restored once the prior VA loan is paid off, which usually happens when that home sells. There are also situations where a borrower can carry two VA loans at the same time, which comes up constantly with PCS moves where the family keeps the old house as a rental.
If you were told no somewhere else, it is worth a second look with a lender who works in this lane regularly.
What is a VA loan assumption, and what does it really cost?
A VA loan can be assumed, meaning a buyer takes over the seller's existing mortgage and keeps the interest rate it was written at. With a large number of loans out there carrying rates nobody is offering today, that is real money over thirty years. Both veterans and non-veterans can assume a VA loan if they meet the lender's requirements.
Here is the part that gets left out of the conversation. The buyer has to pay the seller's equity in cash at closing. On a $450,000 sale with a $350,000 loan balance, that is $100,000 due up front. Secondary financing can sometimes bridge it, but the lender will count that new debt when qualifying the buyer. An assumption is not a way into a house with less cash. It is a way into a better rate with more cash.
Three more things both sides should understand before anyone gets attached to the idea:
- The assumer pays a funding fee of 0.5 percent of the loan balance, unless they qualify for an exemption.
- An appraisal is not required on an assumption. A buyer may still want one so they are not overpaying for the equity gap.
- If the buyer is not VA eligible, the seller's entitlement stays tied to that loan until it is paid off. That can block the seller from using the benefit on their next home, which is a serious problem for a family that is about to PCS again.
Assumptions also move more slowly than a standard purchase, because the servicer holding the loan sets its own process and timeline. If you are working against a report date, build that in.
How early should you start before a PCS?
Earlier than feels necessary. The pattern we see over and over is a family waiting for official orders, then trying to compress house hunting, inspection, appraisal, and closing into the few weeks before the report date.
Getting pre-approved costs nothing and commits you to nothing. It tells you what you can actually write an offer on, which changes which houses are worth your time. More importantly, the VA appraisal runs on its own schedule and does not care about your orders. That is usually what squeezes families who started late.
If a move is even a possibility six months out, start the paperwork. It keeps its value whether or not the orders land.
What should you know about Boerne and Fair Oaks Ranch specifically?
Boerne sits about thirty miles up Interstate 10 from downtown San Antonio, which puts most of Joint Base San Antonio within a reasonable commute while still landing you in a small Hill Country town with its own downtown and an A-rated school district in Boerne ISD. Fair Oaks Ranch sits between the two, closer in, with larger lots and a golf community at its center.
For families arriving on orders with limited time to look, that geography matters more than it sounds. The difference between living north of 1604 and living in Boerne is roughly twenty minutes of drive time and a completely different school district, property tax rate, and weekend.
It is worth spending an afternoon driving all three before you narrow anything down. If you cannot get here before you have to decide, that is exactly the kind of thing an agent should be doing on your behalf.
Frequently asked questions about VA loans in the San Antonio area
Do you need a down payment for a VA loan in Texas?
No. A VA purchase loan requires no down payment for eligible borrowers with full entitlement, and it carries no monthly mortgage insurance. You will still owe closing costs and, unless exempt, the one-time funding fee.
Who is exempt from the VA funding fee?
Veterans receiving compensation for a service-connected disability, veterans who would receive it but for retirement pay, those rated eligible through a pre-discharge exam, Purple Heart recipients, and many eligible surviving spouses. Only the VA determines exemption, and your lender verifies it through your Certificate of Eligibility.
Can a non-veteran assume a VA loan?
Yes, if they meet the servicer's credit, income, and debt requirements. But the seller's entitlement stays tied to that loan until it is paid off, which can prevent the seller from using their VA benefit on their next home. A veteran buyer can substitute their own entitlement instead, which releases the seller.
How long does a VA loan take to close?
A standard VA purchase generally runs on a similar timeline to a conventional loan, commonly thirty to forty-five days from a signed contract. The VA appraisal and its minimum property requirements are the most common source of delay. An assumption usually takes longer because the existing servicer controls the process.
Is Boerne too far from Joint Base San Antonio?
It depends which installation and which shift. Boerne is roughly thirty miles from downtown San Antonio up I-10, and plenty of military families commute it daily. Fair Oaks Ranch and the far north side cut that meaningfully if commute time is the deciding factor.
We live here too
Rise Property Group is based in Boerne and works across Kendall, Bexar, Comal, and Kerr counties. Blanca Flores on our team has been a military spouse for more than twenty years and works primarily with veterans and active-duty families, with VA loans and loan assumptions as her specialty.
If you are PCSing in or out, or you just want somebody to walk through what your options actually look like before you commit to anything, that conversation is free and there is no pressure attached to it.
One note. We are real estate agents, not lenders or VA representatives. Funding fee amounts, entitlement, and exemption status are determined by the U.S. Department of Veterans Affairs and verified by a VA-approved lender. Confirm the current figures at va.gov or with your lender before making a decision.
Thinking About a Move?
Let's talk through it before the orders land.
Rise Property Group · Keller Williams Boerne · Powered by PLACE
27650 IH 10 W, Suite 107, Boerne, TX 78006
Dainelle Scott
Team Owner | Rise Property Group | Keller Williams Boerne | PLACE
or another way